

Contents
Global machinery production fell by 2.1% in 2024. Interact Analysis, which forecasts that machinery production will turn around by mid-2025 and post annual growth of 3%, anticipates growth overall, even though US tariffs, the decline of industrial giants and the AI arms race are creating uncertainty for manufacturing in 2025.
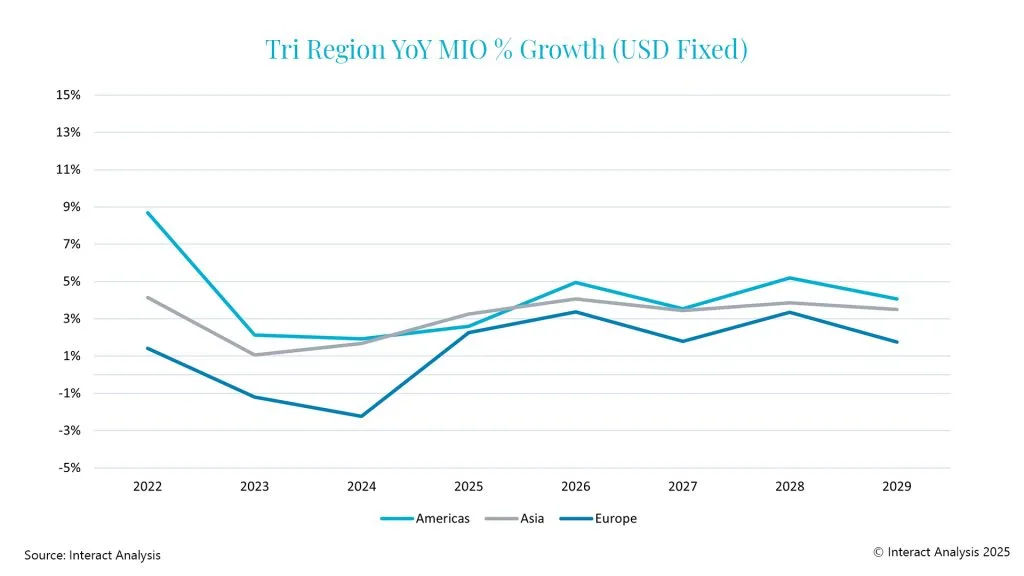
Growth is forecast from 2025 to 2029 for the global manufacturing sector across the European, Asian and American regions.
According to Interact Analysis, global machinery production contracted by 2.1% in 2024. According to the market intelligence specialist’s Manufacturing Industry Output (MIO) Tracker, this downward trend is expected to continue into early 2025; however, by mid-year the market is forecast to turn the corner and post annual growth of 3%.
Looking at manufacturing output, the outlook for 2025 is more uncertain than in recent years. This is partly due to the Trump presidency in the US and the anticipated trade tariffs. In addition, the deteriorating performance of Europe’s industrial giants and the AI arms race have the potential to cause large fluctuations in growth across sectors and regions. Growth similar to that of the machinery sector is also forecast for global manufacturing industry, with steady growth expected from 2025 to 2029 following a significant decline in 2024.
Mixed manufacturing outlook for China, Europe and the US
Growth forecasts for manufacturing industry are lower than they have historically been in many of the major regions. Interact Analysis, which has lowered its long-term outlook for the sector in several key regions such as Germany and Japan, considers its forecasts for emerging regions in Asia to have been too aggressive and has consequently revised them downwards. Forecasts for Europe are also being lowered due to the current economic stagnation. On the other hand, the outlook for US manufacturing is becoming more positive owing to the policies of the Trump administration.
Stronger growth expected for China in 2026 and beyond
China: While a global decline was experienced in 2024, China’s manufacturing industry recorded growth of 1.2%. Although positive compared with the previous year, this marks a very weak year compared with the past growth of Chinese manufacturing.
Throughout 2024, China faced significant challenges such as weak domestic demand, excess production capacity and intense price competition. Despite these challenges, the Chinese manufacturing economy began to improve in Q4, and Interact Analysis has therefore raised its forecasts for 2025. The recovery is expected to be gradual; although factors such as low profit margins for Chinese manufacturers and a potential trade war could further intensify deflationary pressures, stronger growth is expected in 2026 and beyond.
Environmental targets and labour costs challenge Europe
Europe: Europe as a whole is expected to struggle due to high energy costs, self-imposed environmental targets and rising labour costs. In regions such as Germany and the UK, growth remains at very low levels and they are finding it difficult to compete on a global scale. Announcements by German automotive manufacturers of plant closures and mass redundancies are a major source of concern for Germany, as they significantly affect European manufacturing industry.
Risk of retaliation against tariffs for the US
The US showed resilience in 2024 with growth of 2.7%. Interact Analysis states that there are situations that could hinder economic growth in the future, such as the incoming Trump administration’s plans to impose wide-ranging tariffs and the possibility of retaliation by regions targeted by those tariffs. In this scenario, it is emphasised that sectors dependent on components or non-US goods will see their costs rise. Despite these concerns, optimism about US manufacturing persists, as the Trump administration has clearly stated that growing the American economy is its top priority and its policy decisions are expected to reflect this.
Commenting on the Manufacturing Industry Output Report, Jack Loughney, Lead Analyst for the MIO Tracker at Interact Analysis, said: “Machinery production had a difficult 2024, but the outlook for 2025 is much brighter. The sector shrank by 2.1% overall in 2024, but this is expected to be offset by more moderate growth of 3% in 2025. The stagnation of 2024 will continue into the start of 2025, but we predict that by mid-year the sector will have turned the corner.”

Author
Güç Aktarım

 Güç Aktarım (Power Transmission)Güç Aktarım · Kasım 2026Read the latest issue free →